If you've been watching the news lately, you've probably heard that inflation is moving in the wrong direction again. While that may sound concerning, it's important to understand what it actually

Dated: February 2 2026
Views: 46
Buying a home is one of the biggest purchases you’ll ever make. And homeowner’s insurance is what protects that investment. Think of it as your safety net. NerdWallet explains it:
But that peace of mind does come with a cost, and lately those costs have been rising.
There are a number of factors causing insurance premiums to rise today. But, in the simplest sense, here’s what’s driving prices up according to the Insurance Research Council (IRC).
Severe weather events and natural disasters are happening increasingly often, leading to more claims. At the same time, homebuilding materials and labor are more expensive. So, when it comes time to work on those claims, insurers have to manage higher costs to repair or rebuild the affected homes.
That combination adds up to higher premiums. You can see how it’s climbed recently in the graph below. Each bar marks the percentage increase in insurance costs for that calendar year.
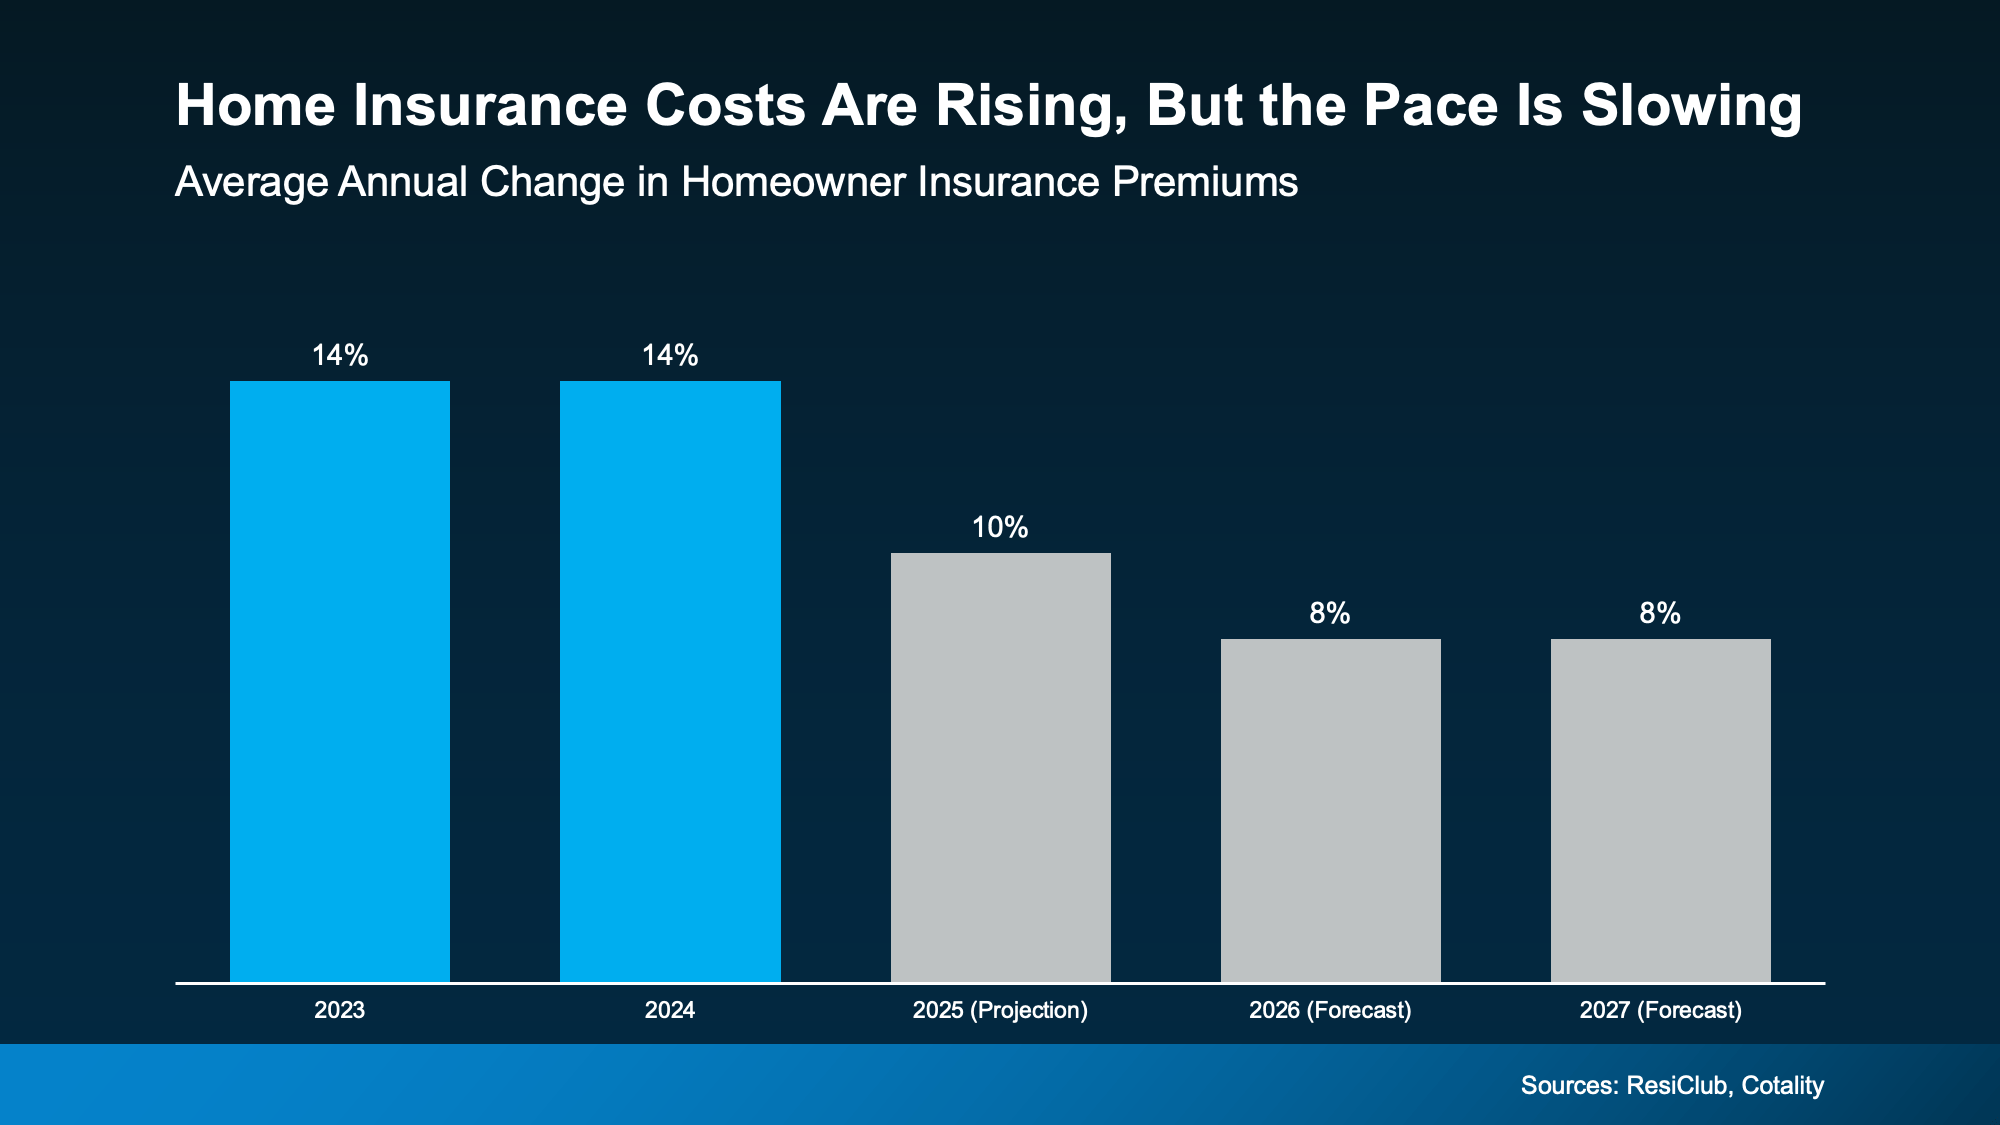 The good news is, the annual pace of the increase may be starting to ease according to ResiClub and Cotality. By their count:
That’s still an increase, but at least the pace is slowing down. And here's another silver lining.
While insurance costs are rising, mortgage rates are falling. And that can help offset some of this expense. As Michael Gaines, Senior VP of Capital Markets, Cardinal Financial, explains:
“Rising taxes and insurance do create pressure, but they don’t erase the benefits of a lower rate . . . A small rate improvement, paired with the right loan program and smart planning, can still make homeownership possible . . . It’s less about one factor canceling another out, and more about helping buyers layer the right solutions together.”
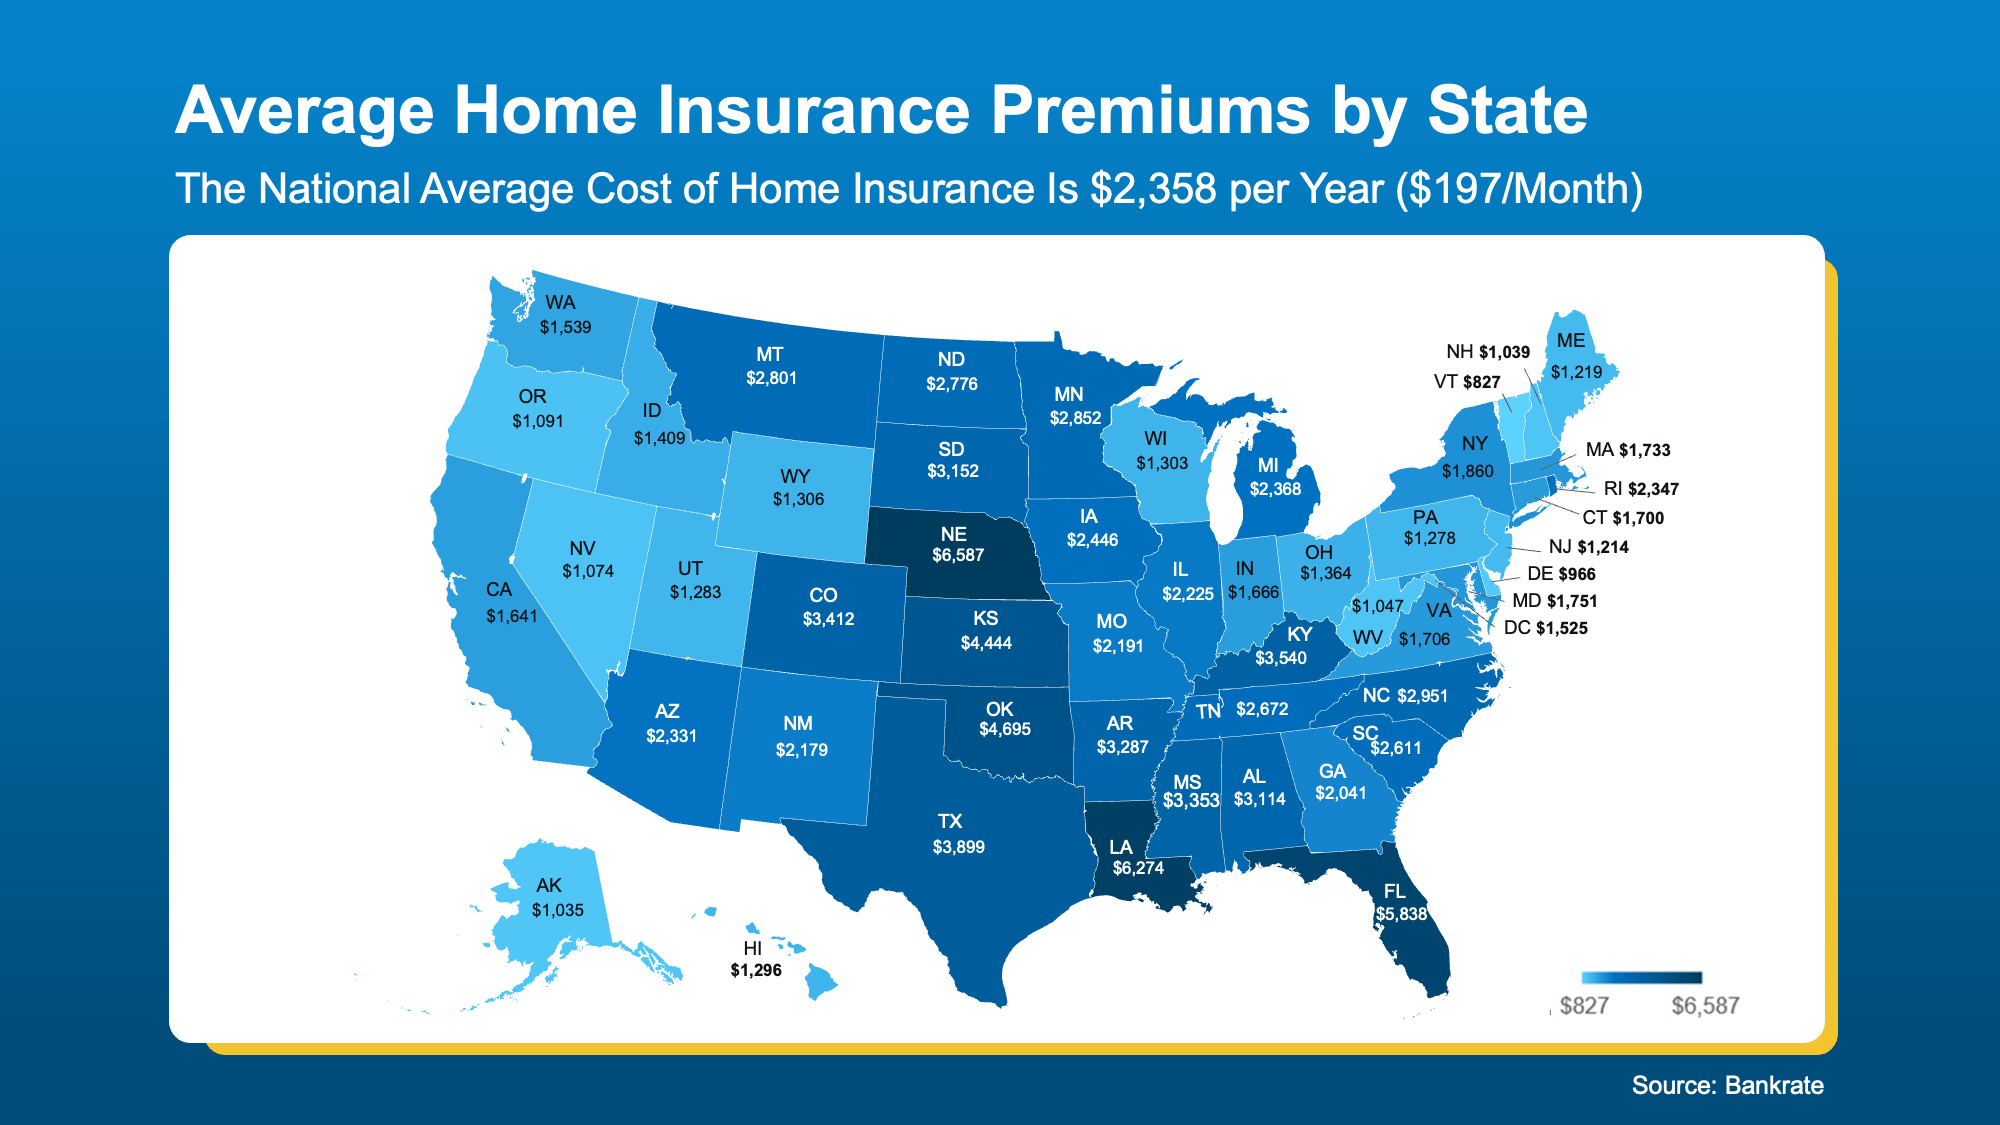
So how much do you need to budget for this? It depends on the price point and location of house, the coverage you need, and more. And just like with everything else in real estate, costs vary by area.
You can get a rough idea of your state’s typical premiums in the map below:
 So, What Can You Do About It?
Generally speaking, your first insurance payment will be wrapped into your closing costs. But after that, it’ll become a recurring expense. That’s why knowing these premiums are rising is so important. It helps you factor that into your budget, so you go in with a full picture of what you can comfortably afford.
If you’re crunching the numbers and trying to find other ways to save, here are a few tips from Insurify and NerdWallet that can help you get the best insurance price possible:
If you’re thinking about buying a home, don’t forget to plan ahead for your homeowner’s insurance.
While costs are rising, knowing what to expect and how to shop around can make a big difference as you’re budgeting for your purchase. Because this isn’t coverage you’ll want to skimp on. It’s your best protection for what’s likely your biggest investment.

As a lifelong resident of Long Island’s South Shore, Dana possesses an intimate knowledge of the area’s charm and diversity. With over 22 years of real estate expertise, she pairs her deep....
If you've been watching the news lately, you've probably heard that inflation is moving in the wrong direction again. While that may sound concerning, it's important to understand what it actually
The Mid-Year Housing Market Update: Why Forecasts Changed in 2026If the Long Island housing market feels a little confusing right now, you're not imagining it.Many buyers entered 2026 expecting
Less House, More Home: Why Smaller Homes Are Paying Off for Today’s BuyersLess House, More Home: Why Smaller Homes Are Paying Off for Long Island BuyersIf you've been searching for a home on
You may be telling yourself you're going to wait to move. Maybe you're hoping mortgage rates will come down, prices will soften, or the market will feel a little less competitive.A lot of people
 OneKey® MLS required Copyright, Source of Data and Disclaimer for IDX display
Information Copyright 2026, OneKey® MLS. All Rights Reserved.
The source of the displayed data is either the property owner or public record provided by non-governmental third parties. It is believed to be reliable but not guaranteed. This information is provided exclusively for consumers' personal, non-commercial use.
The data relating to real estate for sale on this website comes in part from the
IDX Program of OneKey® MLS.
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owner\'s behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
Show More...